What Is Compound Interest and How Does It Work?
Compound interest is the interest you earn on both your original money and on the interest that money has already earned. It’s why a $10,000 investment at 7% grows to $76,123 in 30 years, not $31,000. That difference comes from compounding, and it’s the single most powerful force in personal finance. Whether you’re saving for retirement or paying off a credit card, understanding how it works can mean thousands of dollars in your pocket.
The Simple Math Behind Compound Interest
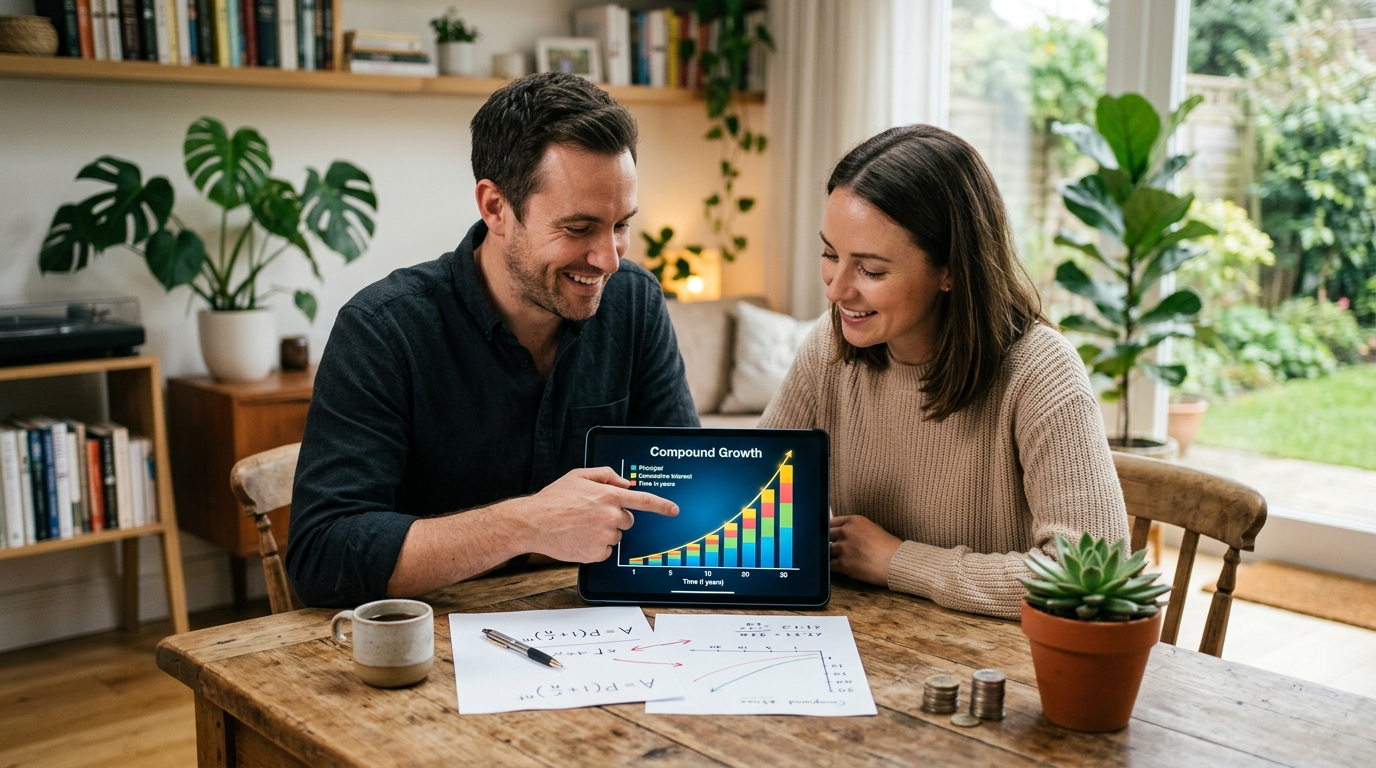
At its core, compound interest follows a straightforward formula: A = P(1 + r/n)^(nt). Here, A is the final amount, P is your starting principal, r is the annual interest rate (as a decimal), n is the number of times interest compounds per year, and t is the number of years. If you invest $5,000 at 6% compounded annually for 10 years, you get $5,000 × (1 + 0.06/1)^(1×10) = $8,954. That’s $3,954 in interest, versus $3,000 with simple interest.
Simple vs. Compound: The Key Difference
Simple interest pays only on your principal. Compound interest pays on principal plus accumulated interest. Over one year, the difference is small. Over 20 or 30 years, it’s enormous. For example, $10,000 at 5% simple interest grows to $20,000 in 20 years. With monthly compounding, it grows to $27,126. That extra $7,126 comes entirely from interest earning interest.
How Compounding Frequency Changes Your Returns
The more often interest compounds, the faster your money grows. Daily compounding beats monthly, which beats quarterly, which beats annually. But the difference shrinks as frequency increases. According to the U.S. Securities and Exchange Commission (SEC), $10,000 at 5% compounded annually for one year yields $10,500. Compounded daily, it yields $10,512.64. That’s only $12.64 more. The real magic happens over decades, not days.
The Rule of 72: A Quick Estimate
Want to know how long it takes to double your money? Divide 72 by your annual interest rate. At 6%, it takes about 12 years (72 ÷ 6 = 12). At 9%, it takes 8 years. This rule isn’t exact, but it’s close enough for quick mental math. Financial planners often use it to show clients why a 1% difference in fees or returns matters over a lifetime.
Compound Interest Works Against You on Debt
Compound interest isn’t always your friend. Credit cards, student loans, and mortgages use it to calculate what you owe. The average credit card APR in the U.S. was 21.47% as of November 2023, according to the Federal Reserve. If you carry a $5,000 balance at 22% APR compounded daily, you’ll owe $6,234 after one year if you make no payments. That’s $1,234 in interest alone. Paying just the minimum can keep you in debt for decades.
How to Use Compounding to Your Advantage
In practice, the best way to harness compound interest is to start early and contribute regularly. A 25-year-old who invests $200 a month at 7% annual return will have about $525,000 by age 65. A 35-year-old who invests the same amount will have only $244,000. That 10-year head start is worth $281,000. Time in the market beats timing the market.
Real-World Examples of Compound Growth
Consider Warren Buffett. According to Berkshire Hathaway’s annual reports, over 90% of his net worth was accumulated after age 65. That’s not because he got smarter; it’s because compounding had decades to work. The same principle applies to retirement accounts. A 401(k) with a 6% employer match can add hundreds of thousands over a career. Vanguard’s 2023 How America Saves report found that the average 401(k) balance for workers aged 55 to 64 was $207,874, but for those who had been saving for 20+ years, it was significantly higher.
Tax-Advantaged Accounts Amplify Compounding
Using a Roth IRA or 401(k) means you don’t pay taxes on gains each year, so more money stays invested. A $6,500 annual Roth IRA contribution at 7% for 30 years grows to $614,000, and withdrawals are tax-free. In a taxable account, the same investment might net you $480,000 after capital gains taxes. The tax wrapper matters almost as much as the return itself.
Common Mistakes That Kill Compounding
- Withdrawing early: Taking out $10,000 from a retirement account at age 30 could cost you over $76,000 by age 65, assuming 7% growth.
- Chasing high fees: A 1% annual fee on a $100,000 portfolio costs you $30,000 over 20 years, according to the SEC’s Investor.gov.
- Ignoring inflation: At 3% inflation, your money loses half its buying power in 24 years. You need returns above inflation to truly compound.
- Starting late: Every year you delay saving $5,000 at 7% costs you about $10,000 in future value by age 65.
How to Calculate Your Own Compound Growth
You don’t need a finance degree. Use a free compound interest calculator from Investor.gov or your bank. Or open a spreadsheet and use the FV function: =FV(rate, nper, pmt, pv). For example, =FV(0.07/12, 30*12, -200, -10000) shows the future value of $10,000 plus $200 monthly at 7% for 30 years. That’s $315,000. Try changing the rate to 5% and see how much you lose. The difference is eye-opening.
Compounding in High-Yield Savings
High-yield savings accounts often compound daily or monthly. As of early 2024, top accounts paid around 5% APY. That’s far better than the national average of 0.46%, per the FDIC. If you park $20,000 in a 5% APY account for five years, you’ll earn about $5,525 in interest. In a 0.46% account, you’d earn just $465. The choice is clear.
Conclusion
Compound interest is either a wealth-building engine or a debt trap. You decide which by how you use it. Start early, contribute consistently, keep fees low, and let time do the heavy lifting. Even small amounts grow into serious money over decades. The math doesn’t care about your income; it cares about your habits. Run the numbers for yourself, then take action. Your future self will thank you.
Q: What is compound interest in simple terms?
Compound interest is interest earned on both your initial principal and on any interest you’ve already earned. For example, if you invest $1,000 at 5% annual interest, you earn $50 the first year. The second year, you earn 5% on $1,050, which is $52.50. That extra $2.50 is the compounding effect.
Q: How does compound interest differ from simple interest?
Simple interest only pays on your original principal. Compound interest pays on principal plus accumulated interest. Over long periods, compound interest produces much higher returns. For instance, $10,000 at 5% simple interest grows to $20,000 in 20 years, while the same amount with monthly compounding grows to $27,126.
Q: What is the formula for compound interest?
The formula is A = P(1 + r/n)^(nt). A is the final amount, P is principal, r is annual interest rate as a decimal, n is number of compounding periods per year, and t is time in years. For example, $5,000 at 6% compounded annually for 10 years gives $8,954.
Q: How can I take advantage of compound interest?
Start investing early, contribute regularly, and reinvest dividends. Use tax-advantaged accounts like a 401(k) or Roth IRA. Keep fees low. Even small amounts grow significantly over decades. For example, $200 monthly at 7% for 40 years becomes about $525,000.
Q: Does compound interest work against me on loans?
Yes. Credit cards and loans charge compound interest on your balance. A $5,000 credit card balance at 22% APR compounded daily grows to $6,234 in one year if you make no payments. Paying off high-interest debt quickly is one of the best financial moves you can make.